• Environ
    • Équipe
    • Carrières
    • Médiathèque
    • Finances
  • Prêts/services
    • Affordable homes
      • For Homebuyers
      • Welcome Home Loans & Coaching
      • Homebuyer Resources
      • Welcome Home Loans - Refinancing
    • ROC Support
      • For Manufactured-home Owners
      • Form an ROC
      • Learn More About ROCs
    • Rocs
      • For Current ROC Residents
      • List of N.H. ROCs
    • Small nonprofit
      • For Small Business & Non-Profits
      • Small Business Loans & Coaching
    • Towns manicipalities
      • For Small Towns & Municipalities
    • Clean Energy
      • Energy Efficiency Solutions
      • Energy Solutions Lending
  • Impact
    • Histoires d’impact
    • Rapports annuels
    • Carte d’impact
    • Partner With Us
  • Politiques/plaidoyer
  • Ressources
    • Bibliothèque de ressources
    • Actualités et perspectives
  • Investir
  • Donner
  • fr
    • en
    • pt
    • fr
    • es
fr
  • en
  • pt
  • fr
  • es
  • Environ
    • Équipe
    • Carrières
    • Médiathèque
    • Finances
  • Prêts/services
    • Affordable homes
      • For Homebuyers
      • Welcome Home Loans & Coaching
      • Homebuyer Resources
      • Welcome Home Loans - Refinancing
    • ROC Support
      • For Manufactured-home Owners
      • Form an ROC
      • Learn More About ROCs
    • Rocs
      • For Current ROC Residents
      • List of N.H. ROCs
    • Small nonprofit
      • For Small Business & Non-Profits
      • Small Business Loans & Coaching
    • Towns manicipalities
      • For Small Towns & Municipalities
    • Clean Energy
      • Energy Efficiency Solutions
      • Energy Solutions Lending
  • Impact
    • Histoires d’impact
    • Rapports annuels
    • Carte d’impact
    • Partner With Us
  • Politiques/plaidoyer
  • Ressources
    • Bibliothèque de ressources
    • Actualités et perspectives
  • Investir
  • Donner
© 2010-26 Fonds d’emprunt communautaire du New Hampshire. Tous droits réservés. New Hampshire Community Loan Fund Inc. est un fournisseur et un employeur qui souscrit au principe de l’égalité des chances. N° d’identification NMLS 253893. Agréé par le New Hampshire Banking Department. Prêteur de logement égal.
  • Politique de confidentialité
  • Politique de confidentialité du site Web
  • Déclaration de non-discrimination
  • Identity Theft: Consumer Education
  • 02
  • 01
  • 03
  • 04
  • 05
  • Environ
    • Équipe
    • Carrières
    • Salle des médias
    • Finances
    • Liste des ROC
  • Prêts et services
    • Acheteurs de maisons préfabriquées
    • Propriétaires de maisons préfabriquées
    • Résidents actuels du ROC
    • Petites entreprises et organisations à but non lucratif
    • Petites villes et municipalités
  • Impact
    • Annual Report
    • Histoires d’impact
    • Politiques et plaidoyer
    • Ressources
    • Idées
    • Investir
    • Contactez-nous
    • Devenez notre partenaire
    • Donner
    • Ouvrir le profil facebook
    • Ouvrir le profil linkedin
    • Ouvrir le profil instagram
  • open facebook profile
  • open linkedin profile
  • open instagram profile
How to get more capital to small businesses?
  1. Home
  2. Insights

How to get more capital to small businesses?

by Personnel du Fonds d’emprunt communautaire
on January 22, 2013
Vfg johnsonprecisionmachine

New York Times blogger and loan broker Ami Kassar recently proposed a different structure for loans as a way to open up small business credit.

Instead of set monthly payments, loan repayment would be based on a percentage of revenues, similar to daily merchant cash advance repayments.
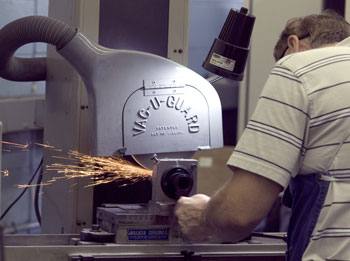
Machine worker at Johnson Precision"In the new model I am proposing, because the lender is assured of a piece of the entrepreneur's future earnings regardless of whether the current business succeeds, the lender should be willing to be more flexible with terms and rates," Ami writes.

I certainly agree with Ami that we need more "out of the box" lending and investing approaches in order to get capital to companies on whose success our economy depends. His proposed solution is similar to what Vested for Growth has done in New Hampshire since 2002.

However, I do not see this type of lending as being the role of bankers, whose "least-cost debt"  business model only works when they are repaid 98-99%. Alternative lenders can take higher risks with subordinate debt as long as the borrower has steady cash flow and a strong management team.

Then there are companies that are primed for growth, but considered too risky for bank-type loans. That's where royalty financing comes in. Similar to what Ami describes, the investor's return is based on the company's performance and cash flow.

Royalty financing works well for second-stage companies that are introducing a new product or experiencing a merger or acquisition. It does not work well for startups, whose revenue is still speculative.

Evolving businesses often travel a wide spectrum of risk. Entrepreneurs are better off when all of the choices along the risk spectrum are available and when they understand the tradeoffs of each.

Partager :
Partager sur FacebookPartager sur LinkedInPartager par e-mail
Partager :
Partager sur FacebookPartager sur LinkedInPartager par e-mail

Inscription à la newsletter